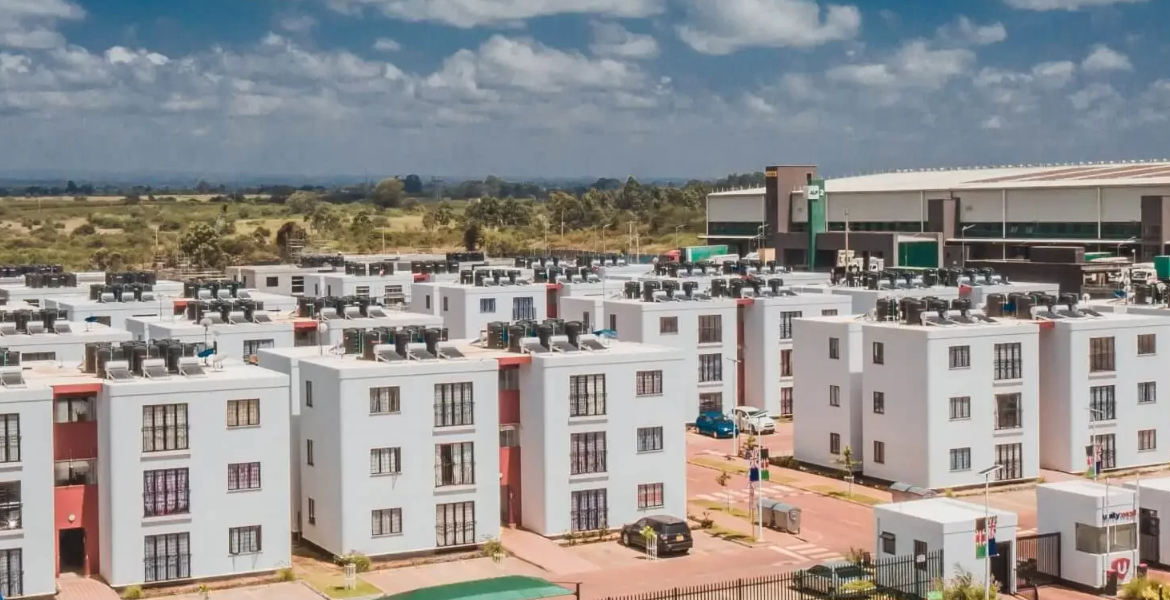
Residential towers rising in Nairobi, Kenya's fast-growing capital
CategoriesBanking and Mortgage Development Energy Investment Real Estate tips & tricks

Invest in Kenya Property Development 2026 | PZ Developers Limited

Why Global Investors Should Choose PZ Developers Limited for Kenya Property Development

Global investors looking for growth beyond saturated Western markets should put Kenya’s property development sector, and PZ Developers Limited, on their shortlist in 2026. East Africa’s largest economy combines a chronic housing shortage, a young urbanising population, strong diaspora capital and a pipeline of national infrastructure. PZ Developers Limited is a Kenyan real estate company that turns those forces into well-located, legally sound developments.

Why Kenya, and why now: the 2026 market in numbers

Kenya builds roughly one home for every four or five it needs, and that gap is the core of the investment case. Industry analysis of Kenya National Bureau of Statistics data puts annual demand at about 260,000 units against fewer than 60,000 formal homes delivered, leaving a deficit above two million units (The Standard, Feb 2026).

What is driving demand in 2026

  • A structural shortage. Real estate and construction contribute an estimated 8 to 9 per cent of GDP, and the shortfall is widening by about 200,000 homes a year (The Star, Jul 2026).
  • Fast urbanisation. Legal practitioners at Garane & Somane Advocates cite urban growth of around 4.3 per cent a year (Chambers Real Estate 2026).
  • Diaspora capital. Central Bank of Kenya data shows remittances above USD 5 billion over the 12 months to April 2026, and property is a favourite long-term destination for that money (BuyRentKenya).
  • Government-backed housing. By mid-2025 more than 45,000 Affordable Housing Programme units were under construction across 37 counties through public-private partnerships, mortgage refinancing and the Housing Levy (The Star).
  • Deeper capital markets. The market has moved beyond bank debt and off-plan cash buyers towards private equity and REITs (Citizen Digital, Jun 2026).
  • Satellite-town growth. New roads, rail and industrial parks are pushing demand beyond Nairobi’s CBD into Kiambu, Machakos and Kajiado.
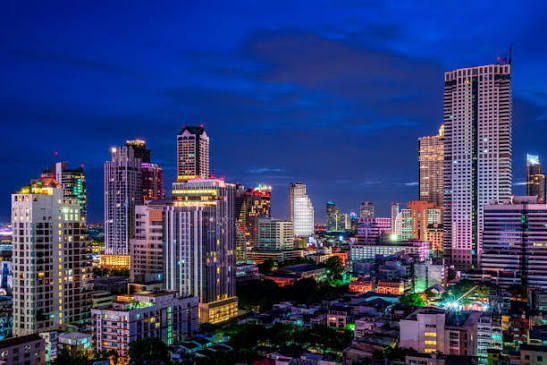
Residential towers rising in Nairobi, Kenya's fast-growing capital
Residential towers rising in Nairobi, Kenya’s fast-growing capital

Where to invest: Kenya’s property corridors compared

Kenya is not one property market but several, each with a different return profile. Global investors usually blend a liquid, income-producing corridor with a higher-growth frontier.

Corridor Main demand drivers Typical product Suits an investor who wants
Nairobi core (Westlands, Kilimani, Lavington, Upper Hill) Corporate, embassy and expatriate tenants; limited land Apartments, serviced units, mixed-use Rental income and liquidity
Nairobi satellite towns (Ruaka, Kiambu, Thika Road, Kitengela, Syokimau) Middle-class home buyers moving out of the city; road and rail links Gated maisonettes, townhouses, off-plan apartments Mid-market growth and resale demand
Konza and Machakos Technology and logistics growth around Konza Technopolis Residential plots, staff housing Medium-term capital growth
Mombasa and Kilifi Tourism, port activity, holiday and retirement homes Beachfront and holiday apartments, villas Lifestyle ownership with rental upside
Lamu County Lamu Port and the LAPSSET corridor Land banking, planned residential and commercial plots Early-stage, long-horizon capital growth

The comparison is a general guide to market character, not a statement of PZ Developers’ current project list. Ask PZ for the live availability and the specific title status of any parcel or unit before you commit.
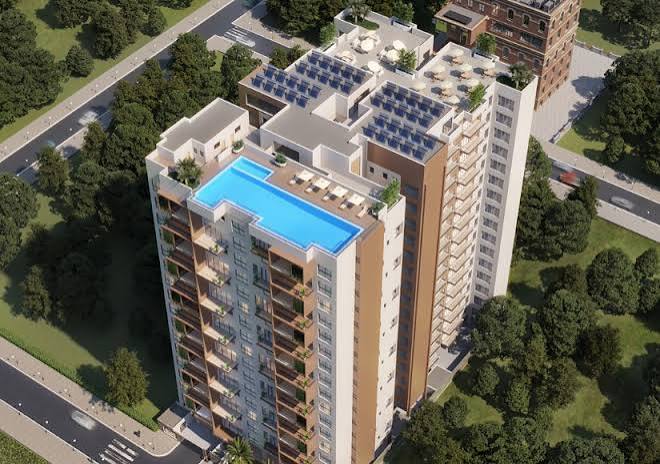
Urban apartments in Nairobi and a coastal property in Kenya.

Seven reasons global investors should consider PZ Developers

  1. A local partner on the ground. Kenyan land and construction involve county approvals, surveyors, advocates and utilities. A resident developer manages these steps for you, so an overseas investor does not have to chase them from another time zone.
  2. Title and legal checks come first. Experienced Kenyan lawyers advise running an official search, confirming the seller’s identity and checking for caveats before any payment. PZ’s process is built around that sequence: search, verify, then transact.
  3. Compliance with Kenya’s foreign-ownership rules. Non-citizens hold land as leasehold of up to 99 years, and any foreign shareholding in a company brings it under the same limit. A developer who structures deals correctly from day one protects your title and your resale value.
  4. Exposure to growth corridors, not just one city. From Nairobi’s satellite towns to the coast and Lamu County, PZ gives you a way to diversify across markets with different risk and return profiles.
  5. Transparent pricing and staged payments. Off-plan buyers in Kenya face real risks around payment structures and delays. Clear schedules, written receipts and milestone-linked payments reduce that exposure.
  6. Built for remote investors. Digital viewings, video site updates, e-signed documents and local representation let you buy, monitor and manage from Dubai, London, Toronto or Johannesburg.
  7. A clear route to exit. Whether you sell a unit, subdivide land or rent a completed home, PZ’s team helps plan the exit from the start, including the capital gains and rental income tax position.

Spotlight: why Lamu County is becoming a frontier for real estate investment

Lamu County offers the rare chance to buy into an infrastructure-led growth story before it matures. The operation of Lamu Port is drawing local and non-local investors to the mainland, and developers say the port’s surroundings, especially Hindi and Mokowe, are emerging as viable residential and commercial locations (Kenya News Agency).

What is driving Lamu

  • Lamu Port and the LAPSSET corridor. The port anchors a planned transport corridor linking Lamu with Garissa and northern Kenya, which is expected to support logistics, trade, industry and new urban centres.
  • Water and services. LAPSSET has announced plans for a KSh 350 million desalination plant serving Mokowe and Hindi, which addresses one of the area’s main constraints (Kenya News Agency).
  • Tourism and heritage. Lamu Old Town is a UNESCO World Heritage Site, which supports long-term demand for holiday and boutique hospitality property.
  • Price history. Business Daily reported years ago that land near the corridor had almost tripled in value on speculation about the project (Business Daily). Past gains are not a guarantee of future ones.

What land costs today (asking prices, not sale prices)

Listing near Lamu Port, Hindi Size Asking price
Prime investment land 15 acres KSh 2.7 million per acre
Tarmac and creek-front land 2 acres KSh 3.5 million per acre
Bora Imani, tarmac frontage and power 7 acres KSh 5 million per acre

These are third-party agent listings from August to October 2026. Prices vary widely with road access, utilities and title type, so use them only to gauge the range.
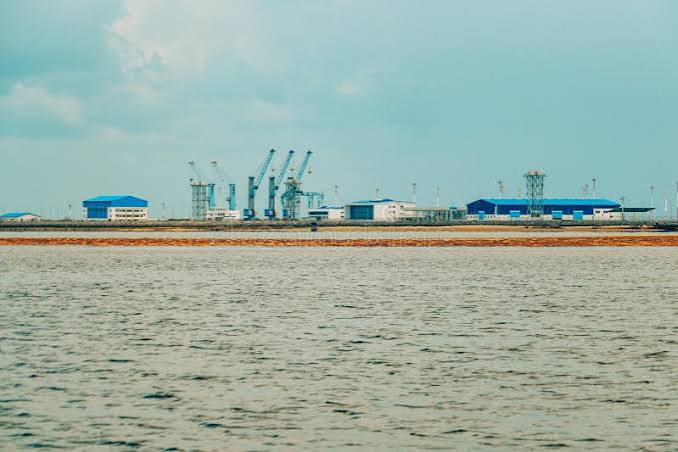
Lamu Port development on Kenya's northern coast
Lamu Port development on Kenya’s northern coast

When to invest. Early-stage corridors reward patience: land banking in Lamu suits investors with a five-to-ten-year horizon who can hold through infrastructure delivery. Before you buy, confirm road access, water and power availability, current security and access conditions, and the title type. Remember that a foreign buyer can hold only a leasehold of up to 99 years, so a plot advertised as freehold must be structured correctly, and agricultural land needs Land Control Board consent.

Foreigners can invest in Kenyan property with confidence once they understand one rule: Article 65 of the Constitution limits non-citizens to leasehold interests of up to 99 years (Kenya Embassy, Washington). Apartments, townhouses, villas and commercial units on leasehold land are all available to foreign buyers.

Key rules at a glance

Topic What to know
Land tenure Non-citizens hold leasehold of up to 99 years. A freehold title held by a foreigner is treated as a 99-year lease.
Companies A Kenyan company with any foreign shareholding is treated as a non-citizen landholder, and a trust cannot be used to get around the limit (CM Advocates).
Agricultural land Transactions need Land Control Board consent, and foreigners face tighter limits (Kenya Embassy).
Unit titles The Sectional Properties Act, 2020 supports individual titles for units in a development (Chambers 2026).
Stamp duty About 4% in urban areas and 2% in rural areas, with conveyancing fees commonly 1% to 2% (Commercial Property Kenya).
Capital gains tax 15% on profit when you sell, per the same guide.
Rental income Non-resident landlords generally declare and pay at year end rather than monthly (Multilaw).
Tax number A KRA PIN is needed for tax and registration.

Tax rates and thresholds change through each year’s Finance Act, so confirm current figures with a Kenyan tax adviser and your home-country adviser before you transact. This guide is general information, not legal or tax advice.

Due diligence checklist before you pay

  • Run an official search at the land registry and confirm the seller matches the registered owner
  • Check for caveats, charges, court orders and unpaid land rates
  • Confirm the title type and that it is correctly structured as leasehold for a foreign buyer
  • Verify approvals: county planning, NEMA environmental clearance and, for agricultural land, Land Control Board consent
  • Inspect the site in person or through a trusted representative, and confirm the boundaries with a licensed surveyor
  • Have your own advocate review the sale agreement and payment schedule
  • Pay only into the advocate’s or developer’s verified account and keep every receipt

Risks to weigh and how a good developer reduces them

Every frontier market carries risk, and an honest developer names it. Chambers’ 2026 review notes that most off-plan investor risk sits in the pre-construction and construction phases, including unregulated developer entry, diverted funds, rigid payment terms and slow lease conversions (Chambers 2026).

Risk How it shows up How to reduce it with PZ
Title defects Fake or disputed ownership, caveats, double sales Official search and independent advocate review before any payment
Off-plan delay Late handover, stalled works Milestone-linked payments and a written completion schedule
Currency movement Shilling moves against your home currency Price in a stable currency where possible and stage transfers
Liquidity Land and large units can take time to sell Choose a realistic holding period and a clear exit plan
Regulatory change Tax or levy changes in a new Finance Act Annual review with a tax adviser

How to invest with PZ Developers, step by step

  1. Discovery call. Share your budget, horizon and goal: rental income, resale or land banking.
  2. Shortlist. PZ presents matching projects with maps, titles, payment plans and photos.
  3. Due diligence. Your advocate and PZ’s team run searches and verify approvals together.
  4. Agreement and deposit. Sign a sale agreement that follows Kenyan law and pay into a verified account.
  5. Construction or development updates. Receive regular photo and video reports against agreed milestones.
  6. Title handover. Receive your leasehold title, then register for rental management or resale support.

Start your Kenya property journey with PZ Developers

Kenya combines a deep housing shortage, rising urban demand and new corridors such as Lamu. The investors who benefit most pair that opportunity with a developer who protects title, communicates clearly and delivers on time. PZ Developers Limited is built for that role.
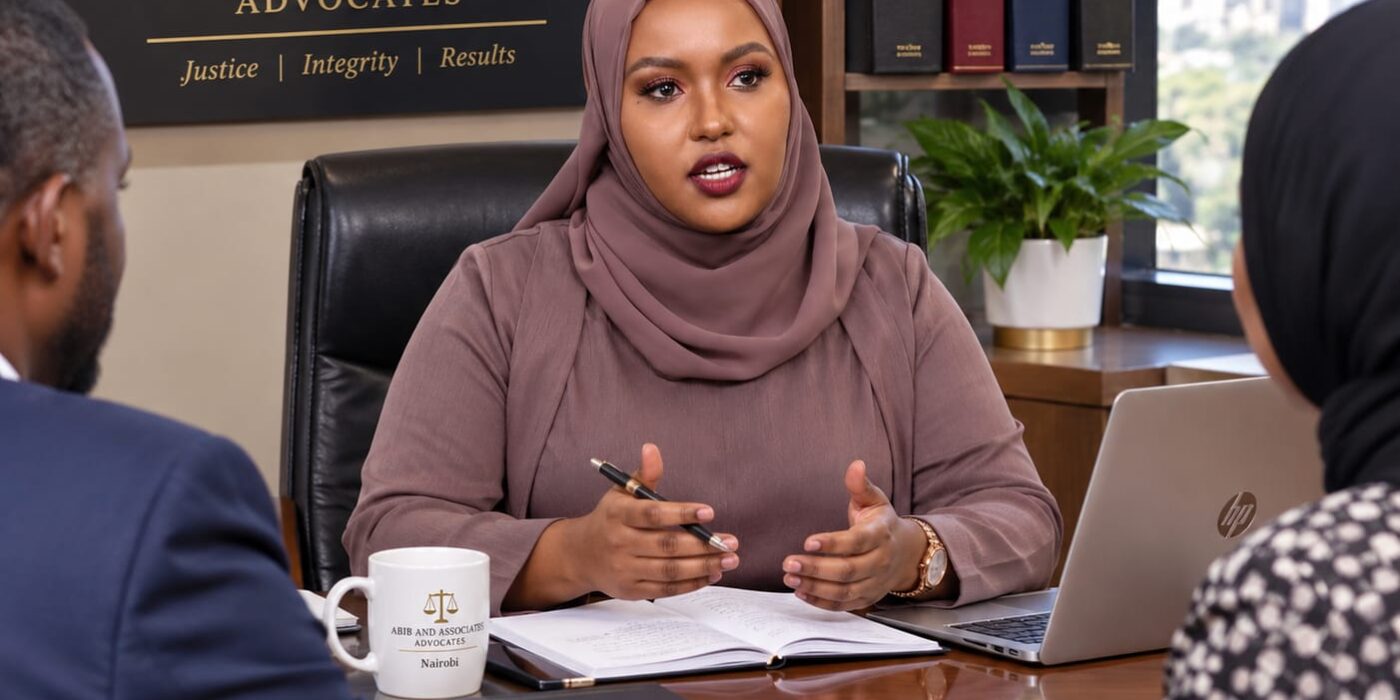
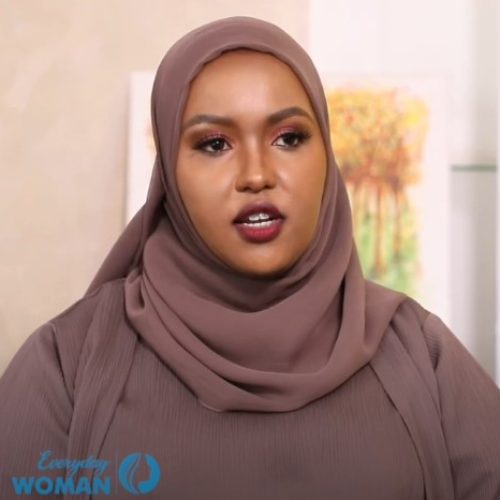
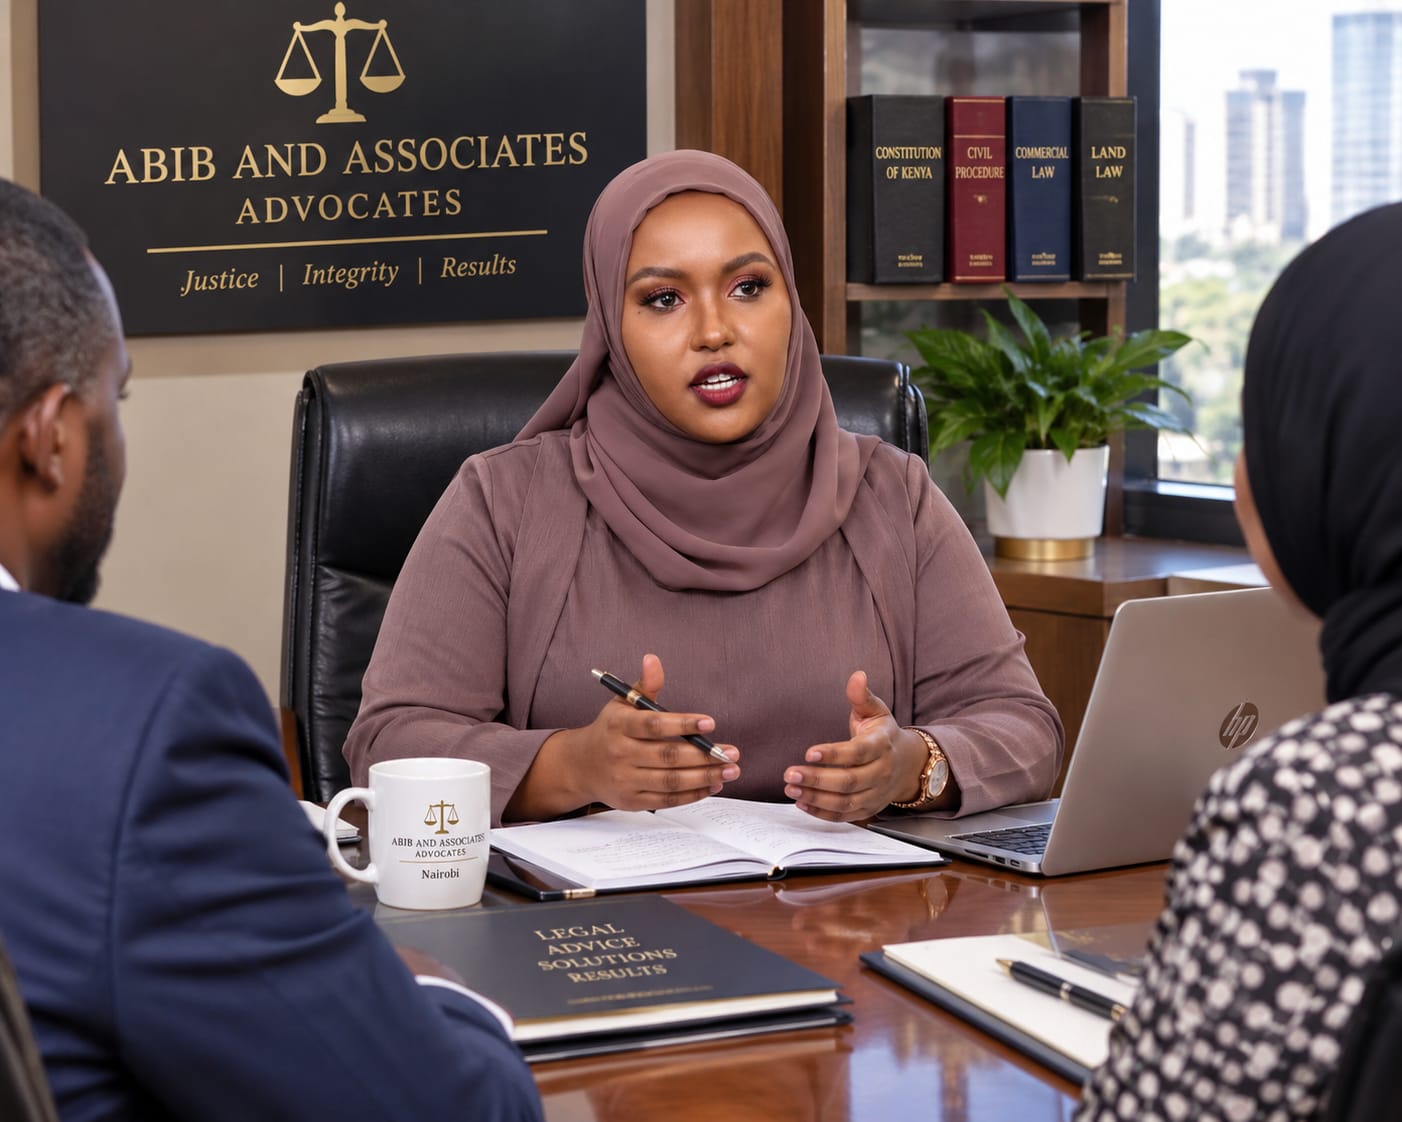
Real estate lawyer Zamzam Abib advising property investors in Nairobi
CategoriesBanking and Mortgage Development Investment Real Estate tips & tricks

ZAMZAM ABDI ABIB:THE NAIROBI PROPERTY LAWYER REAL ESTATE INVESTORS TRUST

ZAMZAM ABDI ABIB:THE NAIROBI PROPERTY LAWYER REAL ESTATE INVESTORS TRUST

Meet Zamzam Abdi Abib, founder of Abib & Associates Advocates and one of the Director in PZ Developers Limited in Nairobi. Expert conveyancing, real estate and commercial legal counsel for property owners and investors in Kenya.

She Turned Legal Expertise Into a Fortress for Property Investors

In Kenya’s real estate market, one wrong signature can cost millions. Zamzam Abdi Abib has built her career making sure that never happens to her clients.


Zamzam Abdi Abib, Managing Partner, Abib & Associates Advocates, Nairobi

A pioneer who built her own table

Kenya’s property market rewards the bold and punishes the careless. Zamzam Abdi Abib is both, and clients get her boldness and her care together.

She graduated with a Bachelor of Laws from the University of Nairobi in 2008, did her pupillage at the leading commercial firm Anjarwalla & Khanna Advocates, and then joined Issa & Company Advocates to set up and head its Conveyancing and Commercial Department. Most lawyers spend years working up to a role like that. She built the department from the ground up.

In 2012 she went further and founded her own practice. Since January 2012 she has been a Partner at Abib & Associates Advocates in Nairobi. As a Somali woman leading a Nairobi commercial law firm, she has become a role model for a new generation of advocates.

Why property owners and investors keep coming back

She is now Managing Partner in charge of the firm’s Conveyancing & Commercial Division, and her specializations include real estate, conveyancing, banking and finance, corporate and commercial law, intellectual property and employment law.

That range matters because a property deal is never only a property deal. It involves:

  • Title verification and due diligence, so you know exactly what you are buying
  • Sale agreements and transfers, drafted to protect your interests
  • Financing and charges, where banking law meets land law
  • Company structuring for investors holding property through entities
  • Dispute prevention, because the cheapest court case is the one that never happens

The firm describes its practice the same way. It offers services in land and property transactions, banking, corporate and commercial law, business organisation and intellectual property, along with commercial, civil, public and criminal litigation. It is also a commissioner of oaths and notary public practice.

Real estate lawyer Zamzam Abib advising property investors in Nairobi

Recognised across the region

Her work has drawn attention beyond the courtroom. The Lawyer Africa included her among its Top Real Estate and Finance Lawyers in Kenya for 2026. Recognition like this reflects a reputation built one transaction at a time.

Who should call her

  • Landowners selling, subdividing or transferring property
  • Developers who need clean titles and airtight agreements before breaking ground
  • Diaspora and first-time investors who want to buy in Kenya with confidence
  • Businesses buying or leasing commercial premises
  • Anyone about to sign a document they don’t fully understand

Get legal advice before you pay a deposit, not after.


Visit or contact Abib & Associates Advocates

Abib & Associates Advocates, City House, 4th Floor, Wabera Street, Nairobi. P.O. Box 43146-00100. Tel/Cell: +254 732 987 060. Email:info@abibadvocates.com.
www.abibadvocates.com

Protect your investment. Book a consultation with Zamzam Abib today.

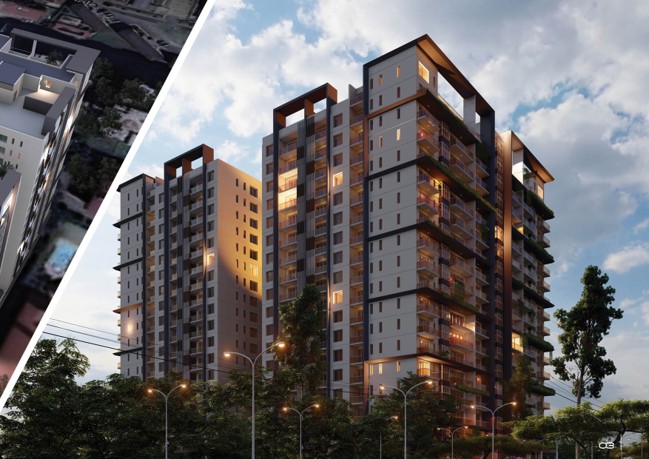
Highpoint 336 Residences rising above Kilimani, Nairobi — 336 executive 2 & 3 bedroom apartments in one of the city's most sought-after neighbourhoods
CategoriesAirbnb Architects Banking and Mortgage Development Investment Real Estate tips & tricks

Highpoint 336: Inside Nairobi’s Most Exciting New Address for Apartments in Kilimani

Highpoint 336: Inside Nairobi’s Most Exciting New Address for Apartments in Kilimani

Everything you need to know about buying a 2 or 3 bedroom apartment in Kilimani, Nairobi — from prices and floor plans to amenities, location and why Kilimani remains one of the best places to invest in Kenyan real estate.


Published by PZ DEVELOPERS LTD Team | Property Guide | 8 min read

Highpoint 336 Residences rising above Kilimani, Nairobi — 336 executive 2 & 3 bedroom apartments in one of the city's most sought-after neighbourhoods.
Highpoint 336 Residences rising above Kilimani, Nairobi — 336 executive 2 & 3 bedroom apartments in one of the city’s most sought-after neighbourhoods.

If you have been searching for apartments for sale in Kilimani or comparing the best real estate investment opportunities in Nairobi, you have probably already noticed the name Highpoint 336. Tucked into the heart of Kilimani — arguably Nairobi’s most in-demand residential and commercial address — Highpoint 336 Residences is a boutique development of 336 executive 2 and 3 bedroom apartments designed for young professionals, growing families and seasoned property investors alike.

In this guide, we walk through what makes this Kilimani apartment development stand out in Kenya’s competitive property market: the location, the design, the amenities, the unit options and the developer behind it all.

City Living, Re-Imagined

Highpoint 336 is described by its developers as their most prestigious project yet — a bespoke residence offering the amenities of a five-star hotel with the exclusivity of a private member’s club. For anyone comparing luxury apartments in Nairobi, that combination of hospitality-grade finishes and boutique scale (rather than a mega-tower of thousands of units) is a key differentiator.

With its Tier 1 location, outstanding specification and unrivalled amenities, Highpoint 336 embraces Kilimani’s charm and character while setting a new benchmark for inner-city living in Nairobi.

Why Kilimani Is Nairobi’s Most Sought-After Address

Ask any real estate agent in Nairobi where the demand is, and Kilimani will come up almost immediately. Once a quiet residential suburb, it has grown into a vibrant, well-connected hub that blends residential apartments, offices, restaurants and lifestyle amenities — making it one of the top property investment areas in Nairobi for both end-users and buy-to-let investors.

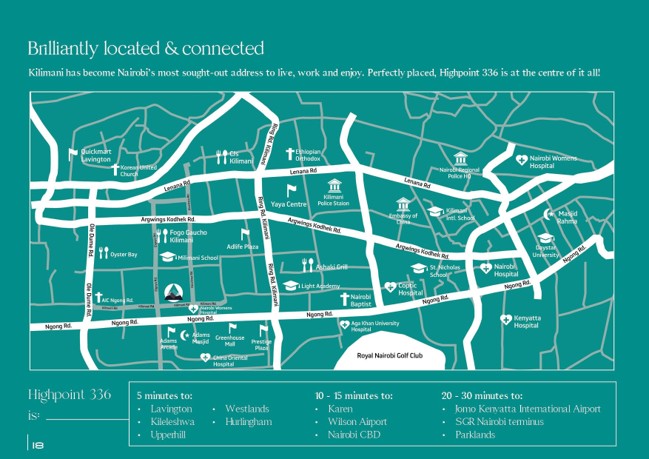
Highpoint 336 is brilliantly located and connected within Kilimani, close to schools, hospitals, malls and Nairobi's major road network.
Highpoint 336 is brilliantly located and connected within Kilimani, close to schools, hospitals, malls and Nairobi’s major road network

 Highpoint 336 is:

5 minutes to

10–15 minutes to 20–30 minutes to
Lavington, Kileleshwa, Upperhill, Karen, Wilson Airport, Nairobi Jomo     Kenyatta     International
Westlands, Hurlingham CBD Airport, SGR Nairobi Terminus,
Parklands

This kind of connectivity is exactly why buyers searching for apartments near Nairobi CBD or property close to Westlands and Upperhill keep circling back to Kilimani — you get inner-city convenience without sacrificing the neighbourhood feel.

Resident-Only Lifestyle Amenities

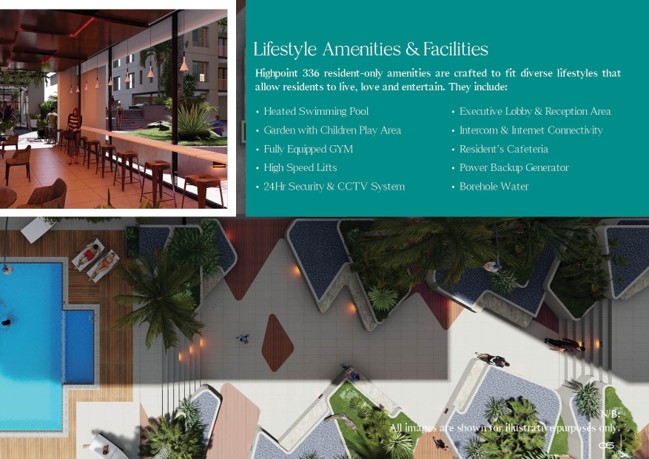
Beyond location, what buyers increasingly look for in modern apartments in Nairobi is a genuine lifestyle offering. Highpoint 336’s resident-only amenities are designed to let residents live, love and entertain, and include:

  • Heated swimming pool
  • Garden with children’s play area
  • Fully equipped gym
  • High-speed lifts
  • 24-hour security & CCTV system
  • Executive lobby & reception area
  • Intercom & internet connectivity
  • Resident’s cafeteria
  • Power backup generator
  • Borehole water
The heated pool, landscaped garden and lounge deck at Highpoint 336 — five-star hotel-style amenities for residents.

For investors, amenity-rich buildings like this consistently command stronger rental yields and resale value — a key consideration if you are weighing rental property investment in Nairobi against other Kenyan asset classes.

Discerning Living: Interior Design & Finishes

Highpoint 336’s unique geometric form makes a bold design statement, but the same impeccable taste and attention to detail runs throughout every apartment. Whether you choose a 2-bedroom or 3-bedroom unit, each home is elegantly proportioned and immaculately finished — the pinnacle of boutique city living.

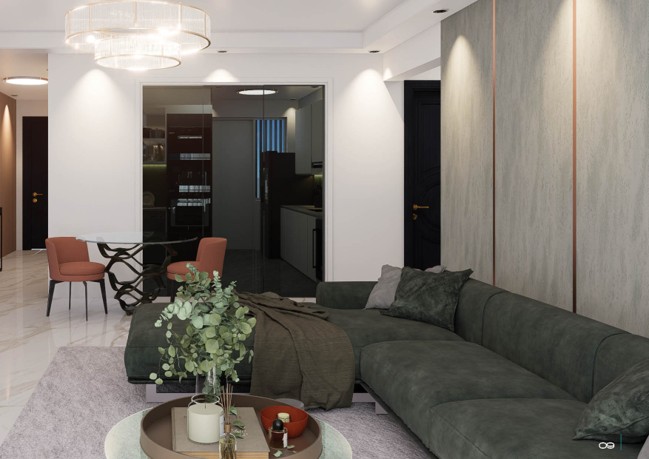
Open-plan living and dining areas are finished with contemporary, hotel-inspired materials and warm lighting.

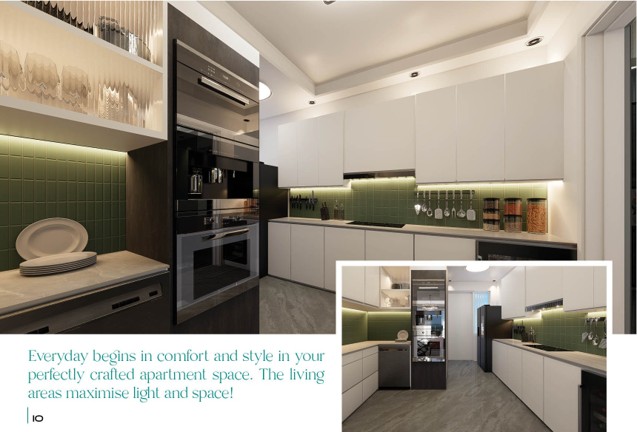
Every day begins in comfort and style. Kitchens are fitted with quality cabinetry and integrated appliances, and are designed to maximise both light and usable space — a detail that matters for anyone comparing fitted kitchen apartments in Nairobi.

Sleek, fully fitted kitchens with integrated appliances and ample storage.

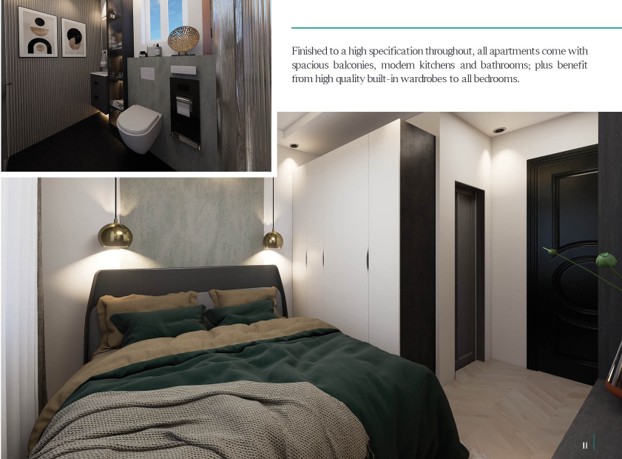
All apartments come with spacious balconies, modern bathrooms and high-quality built-in wardrobes to every bedroom — the kind of finish that makes move-in day simple and keeps long-term maintenance costs low.

Bedrooms feature built-in wardrobes, designer lighting and soft, calming palettes.

Unit Types: Which Highpoint 336 Apartment Fits You?

One of the biggest questions for anyone shopping 2 and 3 bedroom apartments in Kilimani is simply: how much space do I actually get? Highpoint 336 offers five distinct layouts, from efficient 2-bedroom homes to expansive 3-bedroom, all-ensuite residences.


Unit Type Configuration Size Highlights
 

Type A


3 Bed, all ensuite


141.21 m² / 1,519.97 ft²

Entry walkway, open kitchen, two balconies, laundry area
 

Type B


3 Bed, all ensuite


217.1 m² / 2,336.85 ft²

Walk-in closet, pantry, detached DSQ, three balconies
 

Type C


2 Bed, master ensuite


99.1 m² / 1,066.70 ft²

Semi-closed kitchen, guest washroom, large balcony
 

Type D


2 Bed, master ensuite


111.17 m² / 1,196.62 ft²

Pantry room, extended balcony with laundry area
 

Type E


2 Bed, master ensuite


107.53 m² / 1,157.44 ft²

Dedicated dining space, extended balcony & laundry

Every layout includes an entry walkway, dedicated dining area and thoughtfully zoned bedrooms — practical touches that matter whether you plan to live in the unit or list it as a rental apartment in Kilimani.

A Distinctive, Trusted Developer

Choosing the right developer is arguably the single most important decision in any Kenyan property purchase. Highpoint Developers Ltd and PZ Developers Ltd are the leading property group with over 10 years of experience building, selling and managing boutique projects across Kenya. Their track record of past projects — delivered on schedule and fully occupied by happy investors and tenants — includes:

  • ENZI Heights – Mombasa Road
  • CHELEZO Apartments – Kilimani
  • URBAN PARK – Mombasa Road
  • KINGSTONE Residences – Ngong Road
  • RIZIKI Apartments – Kileleshwa
  • CHERRYWOOD – Kilimani
  • MPUUGA Gardens – Kilimani
  • VILLA Lavender – Lavington


This kind of delivery history is exactly what due-diligence-minded buyers should look for when researching trusted real estate developers in Kenya — a proven pipeline of completed, occupied buildings rather than a single, untested project.

Boutique City Living for Every Kind of Buyer

Highpoint 336 Residences offer a contemporary lifestyle to all discerning investors. Whether you are:


  • A young professional making your first move into real estate investment in Kenya,
  • A young family searching for your forever home in a well-connected Nairobi neighbourhood, or
  • An experienced investor expanding a property portfolio with a proven developer,

you’ll find a home that fits your vision among the wide range of apartment units on offer at Highpoint 336.

Ready to Explore Highpoint 336?

Book a site visit or request a full brochure and pricing for the Kilimani’s newest Project.

  • info@pzdevltd.com
  • sales@pzdevltd.com


CategoriesBanking and Mortgage Development Investment Real Estate

Why Most Kenyans Living Abroad Prefer Investing Back Home in Real Estate

Why Most Kenyans Living Abroad Prefer Investing Back Home in Real Estate

Introduction

For millions of Kenyans living and working abroad, the dream of maintaining a strong connection with home remains deeply rooted. Whether they reside in the United States, United Kingdom, Canada, Australia, the Middle East, or elsewhere, many diaspora Kenyans consistently channel a significant portion of their savings into investments back in Kenya. Among the various investment options available, real estate continues to stand out as the preferred choice.


From purchasing land and building homes to investing in rental apartments, commercial properties, and gated communities, diaspora investments are playing a crucial role in shaping Kenya’s real estate landscape. But what makes real estate so attractive compared to stocks, bonds, businesses, or savings accounts?


The answer lies in a combination of emotional attachment, financial security, wealth creation, and confidence in Kenya’s long-term growth prospects.


1. Real Estate Offers a Tangible Asset

One of the biggest reasons Kenyans abroad gravitate towards real estate is the comfort of owning something tangible. Unlike shares or other financial instruments that exist primarily on paper or digital platforms, land and property can be physically seen, visited, and passed down to future generations.


For many diaspora investors, there is a sense of reassurance in knowing that their hard-earned money has been converted into a visible asset. A piece of land in Nairobi, Kiambu, Nakuru, Mombasa, Kisumu, or emerging satellite towns represents more than just an investment—it symbolizes progress, stability, and achievement.


The saying “land never disappears” resonates strongly among many Kenyans who view property ownership as one of the safest ways to preserve wealth.


2. A Strong Desire to Maintain Ties with Home

Investing in Kenyan real estate is often driven by more than financial considerations. Emotional and cultural factors play a significant role.

Many Kenyans abroad envision returning home someday, whether for retirement, entrepreneurship, or family reasons. Purchasing land or building a home creates a sense of belonging and provides a future base should they choose to relocate.

Property ownership also strengthens family connections by ensuring that investments remain within communities where roots, traditions, and relationships have been established over generations.

For many diaspora families, real estate serves as a bridge between their present lives abroad and their future aspirations in Kenya.


3. Long-Term Capital Appreciation

Historically, many regions in Kenya have experienced substantial growth in land and property values. Areas that were once considered remote have transformed into thriving residential and commercial hubs due to infrastructure development and urban expansion.

The growth of bypasses, highways, industrial parks, technology hubs, and commuter transport systems has increased demand for property in previously overlooked locations. As cities continue to expand, investors who enter the market early often benefit from significant appreciation over time.

Diaspora investors are particularly attracted to this potential because real estate offers an opportunity to build wealth steadily while benefiting from Kenya’s growing population and urbanization trends.


4. Protection Against Inflation

Inflation remains a concern in many economies around the world. Rising costs can gradually erode the value of money sitting in savings accounts.

Real estate is widely regarded as a hedge against inflation because property values and rental income often rise over time alongside the cost of living. This ability to preserve and potentially increase purchasing power makes property an appealing investment vehicle for diaspora investors seeking long-term financial security.

Instead of leaving savings idle, many choose to acquire land or property that can appreciate and generate value over the years.


5. Opportunities for Passive Rental Income

Many Kenyans abroad seek investments that can generate consistent income without requiring their daily involvement.

Rental properties offer exactly that. Whether through residential apartments, student housing, commercial premises, holiday homes, or mixed-use developments, real estate provides opportunities for recurring rental income.

With professional property management services becoming more accessible, diaspora investors can own income-generating assets while continuing their careers abroad. This creates an additional income stream that can supplement earnings, support family members, or contribute to retirement planning.


6. Confidence in Kenya’s Growing Urban Population

Kenya continues to experience rapid urbanization, with increasing demand for housing, commercial spaces, and supporting infrastructure.

As more people move into urban and peri-urban areas, the demand for quality housing continues to grow. This trend presents opportunities for investors who recognize that real estate demand is fundamentally linked to population growth and economic activity.

Diaspora investors often view this demographic trend as a strong indicator that property demand will remain robust in the years ahead.


7. Real Estate Provides a Legacy for Future Generations

For many Kenyans, wealth is not measured solely by personal success but by the ability to create opportunities for future generations.

Property ownership offers a practical way to build an enduring legacy. Land and buildings can be inherited, developed, leased, or sold by children and grandchildren. This makes real estate one of the most effective tools for intergenerational wealth transfer.

Many diaspora investors are motivated by the desire to ensure their families have a strong foundation regardless of where future generations choose to live.


8. Familiarity and Cultural Trust

While there are numerous investment options available globally, many diaspora Kenyans are more familiar with real estate than complex financial markets.

Property ownership has long been associated with success and financial stability in Kenyan society. Family discussions, community experiences, and historical examples often reinforce the perception that land and property are dependable investments.

This familiarity creates confidence and encourages many diaspora investors to prioritize real estate over investment products they may not fully understand.


9. Infrastructure Development is Creating New Investment Hotspots

The expansion of roads, rail networks, industrial zones, airports, and utility services continues to unlock new real estate opportunities across Kenya.

Areas surrounding major infrastructure projects often experience increased demand from homeowners, businesses, and developers. Diaspora investors who monitor these developments can identify locations with strong growth potential before prices rise significantly.

Infrastructure remains one of the key drivers transforming Kenya’s property market and attracting continued diaspora investment.


10. A Sense of Achievement and Financial Independence

Owning property back home carries significant personal meaning for many Kenyans abroad. It represents years of sacrifice, discipline, and determination.

For individuals who have spent years working overseas, investing in real estate often becomes a visible milestone that reflects their progress and success. It provides a sense of accomplishment while creating a financial safety net for the future.

This emotional reward, combined with the financial benefits of property ownership, makes real estate particularly appealing to the diaspora community.


 Challenges Diaspora Investors Should Be Aware Of

While the opportunities are compelling, investing in Kenyan real estate is not without risks. Diaspora investors should exercise due diligence by:

* Verifying land ownership and title documents.

* Conducting official property searches.

* Working with licensed professionals.

* Avoiding pressure-driven investment decisions.

* Visiting project sites whenever possible.

* Ensuring all transactions are properly documented.

* Seeking legal advice before major purchases.

Careful planning and professional guidance can significantly reduce investment risks and improve long-term outcomes.


The Future of Diaspora Real Estate Investment in Kenya

Diaspora remittances continue to play an increasingly important role in Kenya’s economy, and a substantial portion of these funds finds its way into the property sector. As technology improves access to property information, virtual site tours, digital payments, and remote property management, investing from abroad is becoming easier than ever.

The combination of emotional attachment, wealth preservation, rental income opportunities, and confidence in Kenya’s growth trajectory suggests that real estate will remain a preferred investment avenue for Kenyans living abroad for many years to come.


Why 2026 Is the Best Year to Invest in Kenyan Real Estate
CategoriesBanking and Mortgage Development Investment Real Estate

Why 2026 Is the Best Year to Invest in Kenyan Real Estate

Why 2026 Is the Best Year to Invest in Kenyan Real Estate

Kenya’s real estate market has always been a resilient pillar of wealth creation. However, 2026 stands out as a uniquely strategic year for both local and diaspora investors to enter or expand their property portfolios. A convergence of economic stabilization, infrastructure maturity, demographic growth, and policy-driven opportunities positions 2026 as a defining investment window.


1. Market Correction Has Created Prime Entry Prices

Over the past few years, Kenya’s real estate sector has undergone a healthy market correction, especially in urban and peri-urban zones.

  • Property prices in many locations have stabilized after years of rapid escalation

  • Developers are offering competitive pricing, flexible payment plans, and incentives

  • Investors can now enter at values that are significantly more favorable than peak years

By 2026, prices are expected to begin an upward trajectory again, meaning early movers benefit from capital appreciation once demand strengthens.

Investor Insight: Buy during stability, not during hype.


2. Infrastructure Projects Are Reaching Full Impact Phase

Kenya has invested heavily in infrastructure, and by 2026, many of these projects will be fully operational and value-accretive.

Key developments influencing real estate value include:

  • Expanded road networks and bypasses around Nairobi and satellite towns

  • Improved commuter connectivity to areas like Rongai, Syokimau, Ruiru, Kitengela, and Juja

  • Enhanced utilities, water access, and power reliability

Historically, real estate values surge after infrastructure is complete—not during construction. 2026 sits perfectly in that window.


3. Rapid Urbanization and Housing Demand Gap

Kenya’s urban population continues to grow at a fast pace, driven by:

  • Youthful demographics

  • Rural-to-urban migration

  • Expanding middle-income households

Yet, housing supply still lags behind demand, particularly in:

  • Affordable and mid-income apartments

  • Gated community developments

  • Mixed-use residential projects

This imbalance guarantees strong rental demand and low vacancy rates for well-located properties acquired in 2026.


4. Strong Rental Yields Compared to Other Asset Classes

In 2026, real estate remains one of the most stable income-generating assets in Kenya.

Compared to traditional investments:

  • Rental yields remain attractive in urban and satellite towns

  • Property income offers inflation hedging

  • Real estate provides predictable, long-term cash flow

With rising living costs, rental rates are adjusting upward—benefiting landlords while maintaining strong tenant demand.


5. Growing Investor Confidence and Diaspora Participation

Kenya’s property market continues to attract:

  • Diaspora investors seeking secure, tangible assets

  • Institutional buyers diversifying portfolios

  • First-time investors opting for off-plan and structured developments

By 2026, improved transparency, digital land records, and professional property management are enhancing trust and ease of transactions, especially for remote investors.


6. Policy and Regulatory Clarity Supporting Property Ownership

Recent land and housing reforms have improved:

  • Title processing efficiency

  • Apartment ownership structures

  • Investor protection in shared developments

This evolving regulatory environment is encouraging long-term ownership, clearer tenure security, and structured developments, all of which favor serious investors entering the market in 2026.


7. Real Estate Remains a Proven Hedge Against Inflation

As inflation affects savings and cash-based investments, real estate continues to:

  • Preserve value

  • Appreciate over time

  • Generate income while assets grow

For investors seeking wealth preservation and growth, 2026 offers an ideal balance between affordability and long-term upside.


8. Strategic Locations Are Still Undervalued—for Now

Several high-potential locations remain undervalued but are rapidly transforming due to:

  • Population spillover from Nairobi

  • Improved infrastructure

  • New educational, commercial, and healthcare hubs

Investing in 2026 allows buyers to secure property before these areas fully mature and price out late entrants.


Final Thoughts: 2026 Is About Positioning, Not Speculation

Real estate success is rarely about timing the absolute bottom—it’s about positioning yourself before the next growth phase. In Kenya, all indicators suggest that 2026 represents that moment.

Whether your goal is:

  • Capital appreciation

  • Rental income

  • Portfolio diversification

  • Long-term wealth security

2026 offers a rare convergence of opportunity, affordability, and future growth.

CategoriesBanking and Mortgage Development Investment Real Estate tips & tricks

How Kenyan Politics & Governance Are Shaping the Real Estate Industry in 2025

How Kenyan Politics & Governance Are Shaping the Real Estate Industry in 2025

1. The Political Climate Driving Real Estate in 2025

In 2025, Kenya’s political and governance landscape continues to play a pivotal role in shaping real estate trends. While policy uncertainty and governance challenges remain, the government’s strong focus on infrastructure development and institutional reforms is driving investor confidence and market growth.

According to analysts, political stability and predictable regulation are now the top two factors influencing real estate investment decisions.

“Policy certainty has become just as important as location,” one property expert noted during the 2025 Kenya Property Developers Association (KPDA) conference.

 2. Infrastructure Investment: The Game-Changer

The government has channelled KSh 217 billion into infrastructure in the first half of 2025 alone — a 12% increase from 2024. This is fuelling a ripple effect across real estate sub-sectors:

  • Improved roads and transport corridors are opening new residential and commercial zones.
  • Property values in regions benefiting from new infrastructure (like the Coast and Nairobi outskirts) have surged by 20-25%.
  • Kenya’s real estate market posted a 7.8% annual return, outpacing even some advanced markets.

For developers and investors, tracking public infrastructure projects has become as critical as studying land values or zoning laws.

3. Land Policy & Regulatory Reforms

Kenyan politics has also shaped how land use and property development are regulated:

  • County governments are revising land-use zoning and permit processes, directly affecting where buyers and developers focus.
  • The national government is working toward digitizing title registration and land transfers to enhance transparency.
  • The 2025 KPDA theme, “Reset, Reform, Rise,” called for faster approvals, less bureaucracy, and accountability in the property sector.

These reforms aim to restore trust in the land system — long plagued by delays, fraud, and opaque approvals.

4. Governance & Housing Finance

Political and governance reforms are also transforming housing finance in Kenya:

  • The Central Bank’s rate adjustments have made mortgages more accessible.
  • The Kenya Mortgage Refinance Company (KMRC) continues to expand funding for affordable housing.
  • The government’s collaboration with private developers through Public-Private Partnerships (PPPs) is unlocking new housing projects across counties.

This alignment of fiscal policy and governance is helping drive Kenya’s Affordable Housing Agenda, making homeownership more attainable.

5. Governance Risks: The Other Side of the Coin

Despite progress, certain political and governance challenges persist:

  • Land fraud and corruption still threaten investor confidence.
  • Policy reversals or political instability at county level can stall development approvals.
  • Public sentiment about land inequality and elite capture continues to influence urban planning debates.

For developers and investors, incorporating governance risk assessments is now as important as market feasibility studies.

6. The Future: Governance Trends to Watch

Looking beyond 2025, several governance trends will continue shaping the industry:

1.  Expansion of Special Economic Zones (SEZs) and corridor developments
2.  County-level land policy harmonization under devolution
3.  Stronger ESG (Environmental, Social, Governance) requirements in property development
4.  Full digitization of land transactions to curb fraud
5.  New housing finance reforms promoting long-term mortgage stability

These shifts indicate that Kenya’s real estate future will be deeply intertwined with good governance and strategic political leadership.

Real Estate Follows Governance

Kenya’s real estate market in 2025 isn’t just shaped by supply and demand — it’s shaped by policy decisions, infrastructure priorities, and governance quality.

From county zoning to national infrastructure planning, the government’s hand is everywhere in defining property value and investment potential.

In the end, Kenya’s real estate is not just about land — it’s about leadership.


CategoriesBanking and Mortgage Development Investment Real Estate tips & tricks

How New Land Rules on Apartment Ownership Are Transforming Real Estate in Kenya

How New Land Rules on Apartment Ownership Are Transforming Real Estate in Kenya

Kenya’s new land rules allowing individual apartment owners to hold freehold title deeds instead of leasehold documents are transforming real estate ownership. This shift has affected buyers, developers, and the property market today.


A New Dawn for Apartment Ownership in Kenya

Kenya’s real estate sector has entered a new era in the recent few moths. With the implementation of the Sectional Properties Act, 2020 and related land reforms, apartment owners are now able to obtain individual title deeds for their units — a major departure from the old system where entire complexes were registered under one leasehold mother title.

This change has created new opportunities and challenges for property buyers, developers, and investors in the real estate industry. Understanding how these new land rules affect ownership is crucial for anyone participating in Kenya’s fast-growing property market.


From Leasehold to Freehold: What the New Rules Mean

Traditionally, most apartment owners in Kenya held leasehold interests — meaning they didn’t actually own the land beneath their building. The entire development sat on a single mother title held by the developer or a management company. Owners simply had “sub-leases” for their individual apartments.

Now, with the enforcement of the Sectional Properties Act, these developments can be subdivided into individual freehold or leasehold titles — known as sectional titles. Each apartment owner can hold a distinct certificate of title, registered under their own name, showing ownership of their unit and a proportional share of the common areas such as parking, corridors, gardens, and recreational spaces.

This system aligns Kenya with global real estate practices and is aimed at giving homeowners stronger ownership rights and legal protection.


Key Changes Introduced by the New Land Rules

Individual Ownership and Clearer Titles

Every apartment can now be issued a unique title deed — a huge step forward from shared or mother titles. This ensures each homeowner enjoys full ownership rights, including the ability to sell, transfer, or mortgage their property independently.

Impact:

  • Easier property transfer and resale
  • Reduced risk of ownership disputes
  • Stronger confidence among local and foreign buyers

Enhanced Access to Mortgage Financing

Banks and financial institutions are more comfortable lending against individual titles than shared leasehold documents. The new rules make it easier for apartment buyers to use their units as collateral for loans, since each unit now stands as a legally distinct property.

Impact:

  • Increased access to home loans
  • Boost in apartment sales and construction financing
  • Strengthened real estate investment climate

Formalized Management of Shared Amenities

Common areas — such as driveways, playgrounds, lifts, and swimming pools — are now governed by a Management Corporation automatically created under the sectional title plan. All apartment owners are members of this corporation and must contribute to maintenance and insurance of shared spaces.

Impact:

  • Professional management and accountability
  • Legal framework for service charge collection
  • Clear rules for resolving disputes among residents

Better Protection for Buyers and Investors

Before these reforms, developers often retained control over the mother title, making it hard for owners to confirm ownership or secure financing. With individual titles, buyers now receive documented proof of ownership, registered at the Ministry of Lands — offering transparency and legal security.

Impact:

  • Reduced fraud and title duplication
  • Buyers can independently verify ownership through official searches
  • Increased confidence in off-plan investments

Developers’ New Responsibilities

For developers, the law introduces additional obligations. They must prepare geo-referenced sectional plans, surrender the mother title, and register each unit with the Land Registrar before sale or handover. Developers are also required to form and register the Management Corporation on behalf of owners.

Impact:

  • Higher compliance and survey costs
  • Longer project approval timelines
  • Increased transparency and buyer confidence


Broader Impacts on Kenya’s Real Estate Market

Rising Property Values

Properties with individual title deeds generally command higher market prices and sell faster than those without. Buyers perceive them as safer investments with fewer legal complications.

Improved Urban Planning

County governments now have clearer data on property boundaries and can collect rates more efficiently. This supports better urban infrastructure planning, zoning enforcement, and service delivery.

Increased Market Liquidity

Secondary sales are faster and smoother because each apartment can be transferred independently. This improves liquidity in the real estate market, attracting both local and foreign investors.

Professionalization of Property Management

The requirement for legally recognized management corporations is fostering professional property administration. Complexes are better maintained, and governance is more transparent, helping preserve long-term property value.

Challenges and Transitional Issues

While the reforms are widely welcomed, they come with practical challenges:

  • Conversion costs: Developers and existing owners must pay for new surveys, sectional plans, and registration fees.
  • Administrative delays: County land offices face backlogs as many older developments seek conversion.
  • Legal awareness: Some owners remain unaware that conversion to sectional titles is now a legal requirement.
  • Disputes over common areas: Shared space responsibilities may trigger new legal conflicts if not managed transparently.

Nevertheless, these challenges are transitional and are expected to stabilize as the system matures.

Opportunities for Buyers and Developers

For buyers:

  • Always verify whether your apartment has an individual title deed or if it’s pending conversion.
  • Conduct a thorough title search at the Lands Registry to confirm ownership details.
  • Review the by-laws of the Management Corporation before buying into a complex.

For developers:

  • Prepare compliant sectional plans early in the project lifecycle.
  • Educate buyers on the new ownership structure and related fees.
  • Work closely with county land offices and licensed surveyors to avoid delays.

For investors:

  • Prioritize developments with individual titles — they have stronger resale and mortgage potential.
  • Monitor the health of management corporations before purchasing rental units.


The Future of Apartment Ownership in Kenya

The transition to individual apartment titles is a game changer. It aligns Kenya’s urban real estate sector with international standards, improves property market transparency, and enhances investor confidence. Over time, this system will make multi-unit housing safer, easier to finance, and more attractive to buyers seeking long-term security.


The move from leasehold to freehold or sectional ownership in shared apartment developments marks a major milestone in Kenya’s property ownership journey. While the conversion process presents short-term hurdles, its long-term benefits — clear ownership, better financing access, professional management, and increased property value — far outweigh the challenges.

Kenya’s real estate sector is evolving toward a more transparent, efficient, and investor-friendly market — one individual title at a time.


What to Consider When Selecting a Mortgage and Bank Company to Finance Your Property Buying
CategoriesAI Technology Architects Banking and Mortgage Development Investment Real Estate tips & tricks

What to Consider When Selecting a Mortgage and Bank Company to Finance Your Property Buying

What to Consider When Selecting a Mortgage and Bank Company to Finance Your Property Buying


Introduction

Buying a property is one of the most significant financial decisions you’ll ever make — and choosing the right mortgage provider or bank can either simplify or complicate the process. With Kenya’s growing real estate market and the availability of various financing options, choosing the best financial institution to fund your property purchase is more important.

Whether you’re a first-time homebuyer, real estate investor, or looking to upgrade, it is very vital to put this into consideration to avoid uncertainty along the process.


Why Your Choice of Mortgage Provider Matters

Your mortgage or home loan will likely be a long-term financial commitment—typically spanning 15 to 25 years or even more. A poor decision can lead to:

  • Higher-than-expected interest payments
  • Unfavourable repayment terms
  • Hidden fees and penalties
  • Legal complications during title transfer or valuation

On the other hand, the right bank or mortgage provider can offer:

  • Affordable interest rates
  • Flexible repayment plans
  • Good customer service
  • A smooth and stress-free loan processing experience

1. Interest Rates: Fixed vs Variable

Compare Rates Across Banks

Interest rate is arguably the most important factor when choosing a mortgage provider. Kenyan banks offer both fixed and variable (floating) interest rates.

  • Fixed rate: Your rate remains the same throughout the loan period.
  • Variable rate: The rate changes based on market conditions or the bank’s base rate.

Tip: Compare APR (Annual Percentage Rate) — which includes fees — not just the base interest rate.

Popular Kenyan banks offering mortgages:

  • KCB Bank Kenya
  • Standard Chartered
  • NCBA
  • Co-operative Bank
  • Absa Bank Kenya
  • HF Group (Housing Finance)

2. Loan Tenure and Repayment Flexibility

Different lenders offer varied repayment durations, usually from 5 to 25 years. Choose a mortgage with:

  • Flexible tenure that matches your financial capacity
  • Early repayment options without heavy penalties
  • Options to restructure payments if your income changes

Pro Tip: A longer tenure lowers monthly instalments but increases total interest paid. Strike a balance.

3. Loan Processing Speed and Approval Time

Time is money in real estate. Some banks have fast loan processing procedures, while others may take weeks due to paperwork, title verifications, or internal bureaucracy.

Ask:

  • How long does it take to approve the mortgage?
  • What documents are required?
  • Is pre-approval available?

4. Hidden Charges and Fees

Beyond the interest rate, there are often undisclosed or poorly explained costs, such as:

  • Loan processing fees
  • Legal fees
  • Valuation fees
  • Stamp duty and registration costs
  • Insurance charges

Always request a full loan cost breakdown before signing anything. It’s also highly advisable to always engage an advocate or anyone with proper understanding to read for you the documents to undisclosed the hidden clues in the paperwork.

5. Customer Support and Transparency

A good mortgage provider should be easy to reach, responsive, and transparent. This is especially important when you need:

  • Loan statements
  • Clarifications on interest fluctuations
  • Help restructuring your loan

6. Eligibility Criteria

Different banks have different qualification requirements based on:

  • Income level
  • Employment status (salaried vs self-employed)
  • Age
  • Existing debts and credit score

Make sure the bank’s eligibility terms are clear and realistic based on your income or business structure.

7. Property Type and Location Restrictions

Some lenders only finance specific types of property or require that the property:

  • Be located within urban zones
  • Have a clean title
  • Be part of a registered project
  • Be residential rather than commercial

If you’re buying land, a shell house, or off-plan property, verify if the bank will finance that type of purchase.

8. Reputation and Industry Standing

Choose a mortgage provider with a proven track record in property financing. Look for:

  • Licensed financial institutions registered by CBK (Central Bank of Kenya)
  • Membership in Kenya Mortgage Refinance Company (KMRC)
  • Awards or recognition in the banking industry
  • Online ratings on Google, HelloPeter, Trustpilot, etc.

9. Partnerships with Real Estate Developers

Some banks have strategic partnerships with trusted developers, offering:

  • Faster approval for partnered properties
  • Lower interest rates or zero processing fees
  • Co-hosted open days and property expos

This can reduce your paperwork and negotiation time.

10. After-Sale Services and Support

You want a lender who’ll stay with you through your repayment journey, offering services such as:

  • Annual mortgage statements
  • Mobile app tracking for payments
  • Insurance bundling (homeowners’ insurance, life cover)
  • Refinancing or top-up loan options

Consider Government-Backed Affordable Housing Schemes

If you’re a low- or middle-income earner, you might qualify for government-supported mortgage programs like:

  • Affordable Housing Programme (AHP)
  • Kenya Mortgage Refinance Company (KMRC) loans

These offer lower interest rates and simplified eligibility criteria.


Selecting the right bank or mortgage company is more than just picking the one with the lowest interest rate — it’s about aligning your financial goals, property ambitions, and long-term peace of mind.

Compare

Ask Questions

Read the Fine Print

Think Long Term

By doing thorough research and knowing what to look for, you’ll ensure your property dream doesn’t turn into a financial nightmare.